It starts with a £3 coffee. Then a direct debit lands a day early. Then the train fare. Each one is trivial; together they push your balance £42 below zero, and your bank charges you for the privilege. Overdraft fees are among the most resented charges in British banking — and among the least understood. In 2026, the rules have changed significantly from the bad old days of £30-a-day penalties, but overdrafts can still quietly drain hundreds of pounds a year from people who never meant to borrow a penny. This guide explains exactly how overdraft fees work now, what they really cost, and the practical steps to avoid them entirely.
How overdraft fees work in 2026
Since the Financial Conduct Authority’s 2020 reforms, UK banks can no longer charge fixed daily or monthly overdraft fees — the regime that once turned a £10 shortfall into a £90 charge. Instead, all arranged overdrafts are priced as a single annual interest rate, typically around 35–40% APR (EAR), with no compounding of fees on fees. Here is what that means in practice: borrowing £500 for a month at 39.9% costs roughly £16. That sounds modest until you realise it is one of the most expensive forms of borrowing available — several times the cost of a credit card, and vastly more than a personal loan. Unarranged overdrafts — going beyond your agreed limit — are where it still gets painful: most banks now simply decline the payment rather than charging, but some still apply interest or return-item charges, and the damage to your financial breathing room is real either way. The FCA’s consumer pages explain your rights clearly, including the requirement that banks show overdraft costs in pounds and pence, not just percentages.
The true cost most people never calculate
Banks quote 39.9% and your eyes glaze over; percentages are abstract. Pounds are not. Someone who sits £800 overdrawn for half the year pays around £160 in interest — for the privilege of spending their own money slightly early. Someone perpetually £1,500 into an arranged overdraft pays roughly £600 a year, every year, indefinitely. That is a holiday, or an emergency fund, or six months of the savings habit you keep meaning to start — converted into bank profit. People who find simple ways to save money on everyday expenses often discover that killing the overdraft habit is the single highest-return “saving” available to them, because the interest rate you stop paying is a guaranteed, tax-free return no investment can match.
Why you keep drifting into the red (it is not just spending)
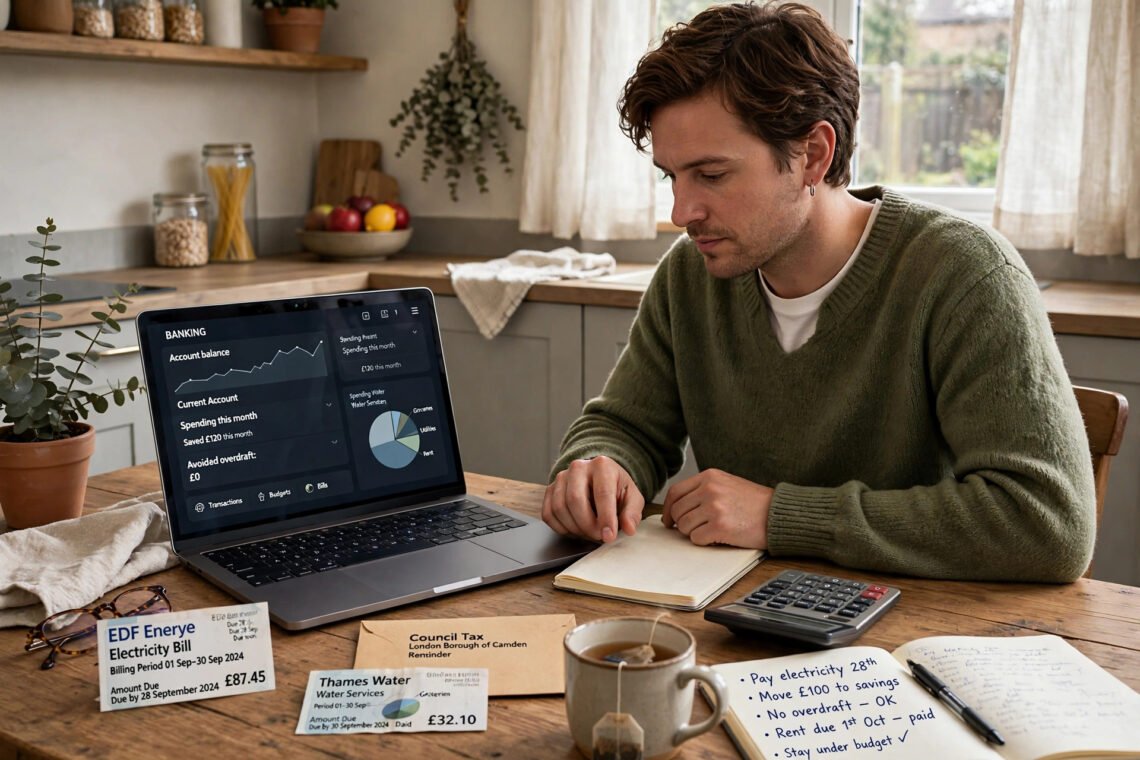
Overdraft use is rarely about reckless spending. The common patterns are structural: direct debits clustered at month-start while pay lands mid-month; irregular freelance income against fixed bills; the “buffer illusion” where the overdraft limit feels like part of your balance. Banks know this — the limit is displayed right there in your available balance, a design choice the FCA has repeatedly questioned. The fix starts with mapping: list every regular outgoing with its date, and compare against your pay date. Mismatches are the machine that manufactures overdrafts. Moving two or three direct debits by a week — most providers allow this with a phone call — can eliminate the dip entirely. It is plumbing, not willpower.
The arranged-versus-unarranged trap
An arranged overdraft (agreed limit, ~40% interest) is expensive. An unarranged overdraft (beyond the limit) is worse — declined payments, potential charges, and markers that can affect future borrowing. If you regularly exceed your arranged limit, call the bank and increase it rather than drifting over: the arranged rate, while steep, beats every alternative. Better still, treat any regular overdraft use as a signal to fix the underlying cash-flow timing.
Five practical ways to avoid overdraft fees entirely
First, build a £500 mini-buffer in a separate instant-access savings account — not invested, not locked away, just sitting there as your personal overdraft facility at 0%. Second, set up balance alerts: every UK banking app lets you trigger a notification when your balance drops below a threshold you choose — set it at £200, not £20, so you have time to act. Third, run a weekly two-minute money check every Sunday: upcoming bills versus balance. Fourth, if your pay date and bill dates clash chronically, ask your bank about switching your overdraft off entirely — several banks now offer this, forcing payments to decline rather than silently borrowing. Fifth, for persistent shortfalls, speak to a free debt adviser before the overdraft becomes structural: MoneyHelper both offer free, impartial help, and early conversations are dramatically easier than late ones.
What to do if you are stuck in a permanent overdraft
A permanent overdraft — living in it month after month — is functionally a high-interest loan you never applied for, and banks are now required under FCA rules to identify customers in persistent overdraft and offer help. Take the help. The escape sequence: stop the bleeding first (fix the bill timing), then attack the balance like a debt — smallest, most expensive balance first, using a structured budgeting approach to free up the monthly surplus. Consider whether a 0% money-transfer credit card or a low-rate personal loan would clear it cheaper — 39.9% is almost always beatable. And check your credit file: persistent overdraft usage is visible to lenders and can affect mortgage applications, which is reason alone to clear it before you need to borrow for anything important.
The overdraft-free future: automating the buffer
The permanent fix for overdraft fees is not vigilance — it is automation that makes vigilance unnecessary. Once you have fixed the bill timing and built the initial £500 buffer, set up a simple system: a standing order on payday that tops the buffer account back to £500 automatically, before any other spending. Treat it like a bill — because the alternative is paying the bank’s bill instead. Review the buffer quarterly, not daily; the system should be boring. And once the buffer has survived six months untouched, consider growing it toward £1,000 — the point where most “emergencies” stop being emergencies at all. The psychological shift is the real prize: moving from managing scarcity month to month to operating with a margin. People who make this transition describe the same unexpected feeling — not excitement, but quiet. The low-grade financial anxiety they had normalised for years simply goes silent. That silence is worth far more than the interest saved, though the interest saved is considerable too.
Frequently Asked Questions
Can banks still charge £30 a day for overdrafts?
No. Since April 2020, the FCA banned fixed daily and monthly overdraft fees. All arranged overdrafts must use a single interest rate with no other charges. If you see old-style fees on a statement, complain — and escalate to the Financial Ombudsman if needed.
Does using an arranged overdraft affect my credit score?
Staying within an arranged limit and repaying is generally neutral to mildly negative. Regularly exceeding the limit, or having payments declined, leaves markers that lenders notice. Persistent heavy overdraft use can affect mortgage affordability assessments.
Should I just increase my overdraft limit?
As an emergency measure, an arranged limit beats going unarranged. As a lifestyle, it is one of the most expensive borrowing habits available. Increase the limit to avoid unarranged charges, then work the escape plan.
Are some banks cheaper for overdrafts than others?
Rates cluster around 35–40%, but some banks offer lower rates, interest-free buffers (typically £25–£500), or graduate/student terms. Citizens Advice maintains current comparisons — switching current accounts takes seven days under the Current Account Switch Service.
Overdraft fees are a tax on disorganisation, not a moral failing — but they are a tax you can abolish. Map your bill dates, build the £500 buffer, set the alerts, and treat any month you pay overdraft interest as a system failure to fix, not a bill to accept. The banks redesigned overdrafts to look fairer; your job is to make them irrelevant.