£4,200 on the credit card at 24.9%. £1,800 on the store card at 29.9%. £900 overdraft at 39.9%. The mathematically optimal move is obvious: attack the highest rate first. And yet the mathematically optimal method — the “avalanche” — fails for most people, because humans are not spreadsheets. The debt snowball method works on a different principle: that motivation, not mathematics, is what actually gets debts paid. This guide explains how the snowball method works, why behavioural science backs it, and how to run it on UK debts in 2026.
How the snowball method works
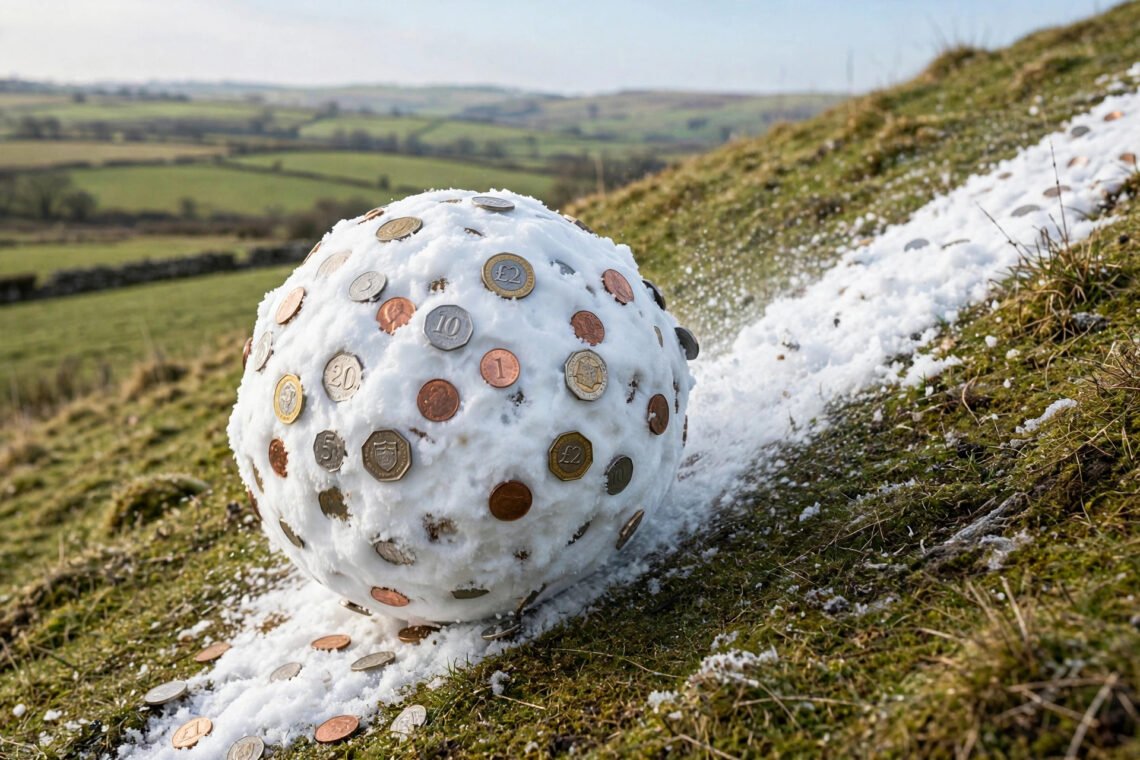
The method has four steps. One: list every debt smallest balance to largest, ignoring interest rates entirely. Two: pay minimums on all of them — never miss a minimum, because missed payments trigger fees and credit-file damage. Three: throw every spare pound at the smallest debt until it is gone. Four: take the entire payment you were making on the cleared debt (minimum plus extra) and roll it into the next smallest — the payment “snowballs” larger with each debt killed. Example: minimums total £180 across three debts; you find £120 extra. The £300/month attacks the £900 overdraft first — gone in three months. Then £300+£40 (the overdraft’s minimum) = £340 attacks the store card. Each victory increases both the payment and your belief. StepChange, the free debt charity, recognises that the method people actually stick with beats the theoretically optimal one — and their advisers see daily proof that motivation is the binding constraint in debt payoff.
Why psychology beats mathematics here
Harvard Business Review-published research found that focusing on the smallest balance first — achieving quick wins — predicts debt elimination better than focusing on interest rates. The mechanism: each cleared debt delivers a dopamine hit of progress that sustains the sacrifice through the long middle months. The avalanche method’s first win can take a year; most people quit by month four. The interest-rate cost of the snowball versus the avalanche is real but usually modest — on typical UK consumer debts, the difference runs to tens or low hundreds of pounds, while the completion-rate difference is enormous. Think of it as paying a small premium for a method you will actually finish. The exception: if two debts are similar in size, attack the higher rate first — you get the psychological win either way. A proper household budget is what produces the “spare pounds” the snowball needs; without the budget, there is no snowball.
Find the extra payment (the part everyone skips)
The snowball needs fuel beyond minimums. Sources that work: the subscription audit (the average Briton wastes £50+/month on unused subscriptions), the food-shop reset (meal planning typically saves £40–£80 monthly), selling the unused (one weekend of listings often raises £200–£500), and the temporary intensity — three months of packed lunches and no takeaways is a sprint, not a life sentence. People finding everyday savings often fund the entire snowball from money they did not know they were spending.
Run it properly: the rules and the traps
Rules: never miss minimums (set direct debits for all of them — automation removes willpower from the equation). Do not take on new debt during the payoff — cut up the cards or freeze them (literally, in ice, if needed). Celebrate each cleared debt modestly — the £20 takeaway, not the £200 spree. Traps: balance-transfer cards can accelerate the snowball (0% for 20+ months on the transferred amount) but only if you close or cut the old card — otherwise you double the debt. Payday loans and high-cost credit must be attacked with urgency regardless of size — their rates compound faster than any snowball rolls. And if the total debt exceeds what the snowball can clear in 2–3 years, or minimums alone are unaffordable, skip the DIY method and get free advice immediately — StepChange, Citizens Advice and National Debtline all offer it, and early help preserves options that late help cannot.
After the last debt: the critical 90 days
Clearing the final debt is euphoric — and dangerous. The newly freed payment (often £300–£500/month) feels like a pay rise, and lifestyle inflation is waiting. The rule: redirect the full snowball payment into savings the day the last debt clears — same standing order, new destination. Build the emergency fund first (£1,000, then one month’s expenses), because without it, the next boiler breakdown restarts the debt cycle. Then redirect toward goals: the deposit, the pension, the investments. The snowball method’s final lesson is its best one: you have just proved you can live on less than you earn and direct the difference with discipline. That skill, pointed at wealth instead of debt, is how financial lives transform.
The debt-free date: calculating yours tonight
Motivation loves a date. Tonight, calculate yours: list every debt with its balance, interest rate and minimum payment, add your extra snowball amount, and project the payoff month by month — a simple spreadsheet or one of the free debt calculators does it in minutes. Write the resulting date somewhere visible: the fridge, the phone wallpaper, the bathroom mirror. “Debt-free by March 2027” transforms the snowball from an abstract method into a countdown — and countdowns are psychologically powerful, turning each payment into visible progress toward a fixed point. Revisit the calculation quarterly: every extra payment, every raise directed at the snowball, every sold item pulls the date closer, and watching it move is addictive in the best way. When the date feels far away, remember the alternative maths: without the snowball, minimum payments alone would keep most debts alive for a decade or more, costing thousands in interest. The date is not just motivation; it is the truth about what your discipline is buying. And if the calculation shows the date is more than three years out despite your best effort, treat that as data, not failure — National Debtline’s free advisers can often restructure what willpower alone cannot. Calculate the date tonight. Then start shortening it tomorrow.
Frequently Asked Questions
Snowball or avalanche — which is really better?
Avalanche saves more interest mathematically; snowball gets finished more often behaviourally. For most people, the snowball’s higher completion rate makes it the better choice. The interest difference on typical debts is modest — the completion difference is decisive.
What if I can’t afford more than minimums?
Then the priority is increasing income or cutting costs to create any surplus — even £20/month starts the snowball. If minimums themselves are unaffordable, that is a debt-crisis signal: contact StepChange or Citizens Advice free before it worsens.
Should I use a balance transfer card with the snowball?
Yes, carefully: transferring the highest-rate debt to 0% accelerates payoff, but only if you (a) have a clear plan to clear it before the 0% ends, and (b) do not run up the old card again. The transfer fee (typically 2–3%) is usually worth it.
How long does the snowball method take?
Depends on the debt and the extra payment: £6,000 of debt with £300/month total payments clears in about 22 months including interest. The method shines brightest on 3–6 debts totalling under £15,000 — beyond that, professional advice may find better structures.
List smallest to largest, pay minimums everywhere, attack the smallest with everything spare, roll each victory into the next. It is not the cleverest method. It is the one that works — because it was designed for humans, not spreadsheets. Start tonight: the list takes twenty minutes, and the first win is closer than it feels.